PepsiCo Research Report
Recent underperformance has created an opportunity to buy this leading global beverage and convenience food company at a substantial discount to peers and it's historical mean valuation.
Overview
PepsiCo (PEP) is a leading global beverage and snack/convenience food company with a complementary portfolio of brands, including Lay’s/Walkers, Doritos, Cheetos, Gatorade, Pepsi-Cola, Mountain Dew, Quaker and SodaStream.
The company is organised into six reportable segments: PepsiCo Foods North America (PFNA); PepsiCo Beverages North America (PBNA); International Beverages Franchise (IB Franchise); Europe, Middle East and Africa (EMEA); Latin America Foods (LatAm Foods); and Asia Pacific Foods.
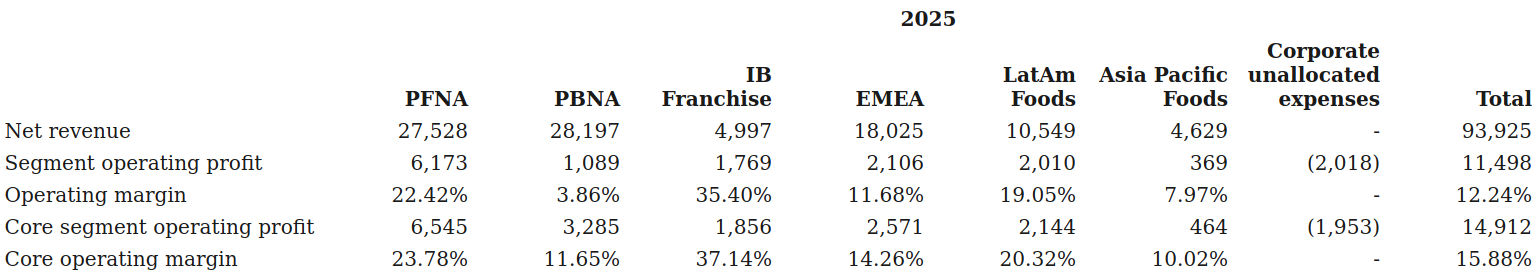
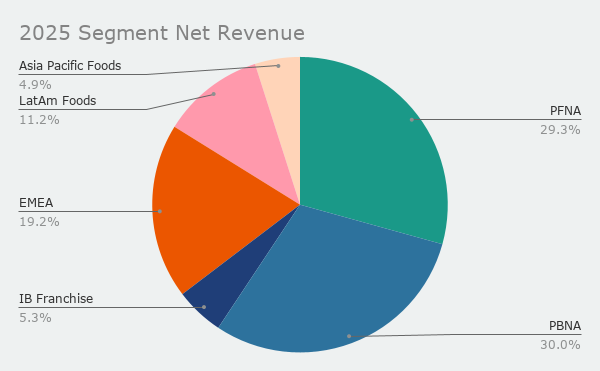
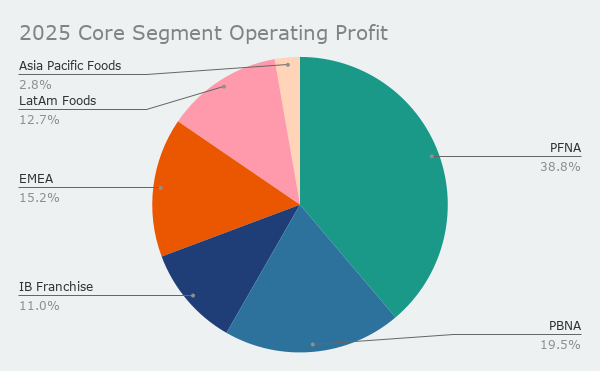
As shown below, the North American segments made up more than half of net revenue and core operating profit in FY25, with a fairly even revenue split between beverages and foods. Notably, however, foods has roughly twice the core operating margin, resulting in a core segment operating profit contribution double that of beverages. While the international segments haven’t massively outgrown North America in revenue terms over the last decade, they have become significantly more profitable. This trend has continued in FY26, with the international business contributing 45% of PepsiCo’s core segment operating profit in Q3.
Varying levels of performance, and the margin divide between food and beverages, has led to calls to split the business. Most prominently, Trian Partners, led by Nelson Peltz, built a stake which exceeded $1.3bn when they published a whitepaper in July 2013 proposing a separation of the (at the time) fast-growing food business from the slower-growth beverage business. Ultimately this split never happened, but the activist campaign did push PepsiCo to make significant cost cuts and reinvest the savings into increased marketing that helped rejuvenate growth in beverages. Trian Partners sold its stake in 2015 after a c.50% gain.
A similar period of soft performance in the last few years has attracted another activist campaign, this time from Elliot Management, which disclosed a $4bn stake on 2 Sep 2025 and wrote a letter to PepsiCo’s management encouraging them to consider strategic actions, including: re-franchising the bottling network (the company bought its two largest bottlers in 2010); selling non-core food assets; and splitting the business, as previously proposed by Trian Partners.
Unlike the early 2010s, this time it’s the whole North American business that’s been struggling, not just beverages. High levels of inflation, in combination with an economically stretched and more health-conscious consumer, have put considerable pressure on the company’s convenient food business. Management has again employed a strategy of cost cuts and reinvestment in marketing, with the addition of price cuts which have helped to support volumes, and investment in new healthier product lines. It remains to be seen whether this will be sufficient to turn the North American business around, or if more substantive changes are required along the lines of those proposed by Elliot Management.
In contrast to North America, the international business segments are in rude health, having collectively grown revenue at least mid-single digits for 22 consecutive quarters and expanded core operating margins by more than 100bps in the first 9M of this year. As you’ll see in the financial analysis below, this strong international performance has helped offset the North American decline, demonstrating the benefits of global diversification.